Every market bubble begins with a sentence that sounds harmless: “This time is different.” Add a few rising charts, a handful of overnight millionaires, a shiny technology story, and suddenly ordinary people are discussing valuations at dinner like they have been managing hedge funds since preschool. That, in plain English, is animal spirits at work.
The phrase “animal spirits” comes from economist John Maynard Keynes, who used it to describe the emotional energy behind economic decisions. People do not invest, spend, borrow, or build businesses using spreadsheets alone. They act because they feel confident, scared, excited, jealous, optimistic, or terrified of missing out. In calm times, those emotions are background music. In a bubble, they become the marching band.
The title “Animal Spirits: This is a Bubble” captures a timeless market question: when does enthusiasm become excess? Not every booming market is a bubble. Sometimes prices rise because earnings improve, technology becomes genuinely useful, or productivity increases. But when prices detach from reality and investors start buying mainly because prices are already going up, the party has moved from investing to musical chairs. The music is loud. The chairs are limited. And nobody wants to be the person standing when the song stops.
What Are Animal Spirits in Investing?
Animal spirits are the human emotions that push markets beyond pure logic. In theory, investors evaluate cash flow, interest rates, growth, risk, and opportunity cost. In real life, they also glance at what everyone else is doing and ask, “Why am I not rich yet?” That little question has launched more bad trades than any spreadsheet error in history.
In financial markets, animal spirits show up as confidence during bull markets and panic during downturns. They influence how investors interpret the same facts. A money-losing company can be called “visionary” during a boom and “uninvestable” after a crash. A risky asset can look like the future on Monday and a flaming shopping cart by Friday.
The Emotional Fuel Behind Bubbles
Bubble behavior usually has three emotional ingredients: greed, fear of missing out, and social proof. Greed says, “I want more.” Fear of missing out says, “Everyone else is getting more.” Social proof says, “If everyone is doing it, it must be smart.” Put those together and you get investors buying assets they barely understand at prices they cannot justify, while assuring themselves that caution is for people who still print boarding passes.
What Makes a Market Bubble?
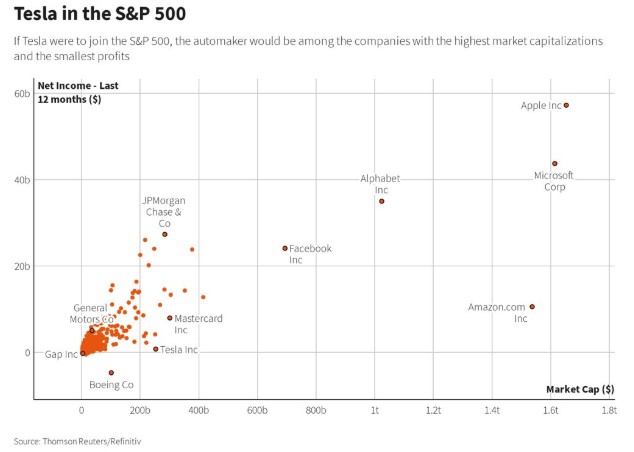
A bubble is not just a high price. Great companies can look expensive for years and still grow into their valuations. A bubble is a pattern: prices rise far faster than fundamentals, storytelling replaces analysis, leverage increases, skeptics are mocked, and buyers depend on finding someone even more optimistic to purchase later at a higher price.
Classic bubble signs include explosive price gains, extreme media attention, easy money, speculative borrowing, celebrity endorsements, retail investor mania, and a sudden belief that old rules no longer apply. The asset can be stocks, homes, crypto, collectibles, private startups, artificial intelligence plays, or even tulip bulbs if history is feeling theatrical.
Bubble Math vs. Bubble Storytelling
Bubble storytelling is seductive because it usually contains some truth. The internet really did change the world. Housing really is essential. Artificial intelligence may transform entire industries. The problem is not always the idea. The problem is the price paid for the idea.
In the dot-com bubble, many investors correctly understood that the internet would become massive. They incorrectly assumed that every company with “.com” in its name deserved a heroic valuation. In the housing bubble, many believed real estate was safe because “homes always go up.” That phrase aged like milk in a hot car when national home prices fell and mortgage losses spread through the financial system.
Why “This is a Bubble” Is Hard to Say in Real Time
Calling a bubble while it is happening is psychologically brutal. Say it too early and you look foolish for years. Say it too late and everyone already knows. A market can be overvalued and still double. Speculation can become more speculative. Expensive can become absurd, then absurd can put on sunglasses and become legendary.
This is why investors should be careful with dramatic predictions. “This is a bubble” may be directionally right but practically useless if timing is wrong. The smarter question is not, “Can I perfectly call the top?” It is, “Am I taking a level of risk that would hurt me badly if the story changes?”
Alan Greenspan and Irrational Exuberance
The phrase “irrational exuberance” became famous in the 1990s when Federal Reserve Chair Alan Greenspan questioned whether asset values had been pushed too high by excessive optimism. The warning was memorable, but the market did not immediately collapse. In fact, the dot-com mania continued before finally breaking in 2000. That is the cruel comedy of bubbles: being early can feel identical to being wrong.
Modern Bubble Behavior: Same Movie, New Costumes
Today’s bubbles look different because the tools are different. In past eras, speculation spread through newspapers, brokers, and cocktail-party gossip. Now it travels through social media, short videos, group chats, podcasts, trading apps, and meme culture. The speed is new. The emotions are ancient.
A stock can become a movement. A coin can become an identity. A startup can become a religion with a pitch deck. Investors do not simply buy an asset; they join a tribe. Once money and belonging mix, logic has to shout over a very loud crowd.
Meme Stocks, Crypto, AI, and the New Speculative Language
Meme stocks showed how quickly online communities can concentrate attention on a small group of names. Crypto cycles showed how revolutionary technology, real innovation, fraud, speculation, and community belief can become tangled together. Artificial intelligence has added another layer: an enormous real-world technological breakthrough paired with market expectations that may or may not be reasonable for every company wearing an AI nametag.
That does not mean every AI stock, crypto project, or fast-rising company is a bubble. It means investors must separate the technology from the valuation. A great invention can still be a terrible investment at the wrong price. A mediocre business can become temporarily thrilling when animal spirits start driving the bus.
How Bubbles Usually Form
Most bubbles move through a familiar cycle. First comes a powerful idea: railroads, radio, the internet, housing, smartphones, blockchain, artificial intelligence. Next comes early success, which attracts capital. Then prices rise, creating headlines. Headlines attract new buyers. New buyers push prices higher. Higher prices create confidence. Confidence becomes overconfidence. Overconfidence becomes leverage. Then reality knocks on the door, usually without texting first.
Stage 1: The Real Innovation
Nearly every major bubble begins with something real. This is what makes bubbles so dangerous. The story is not nonsense. The internet was real. Electric vehicles are real. AI is real. The mistake is assuming that a real trend automatically justifies every valuation attached to it.
Stage 2: The Easy Money Phase
Low interest rates, loose credit, rising liquidity, and strong risk appetite can make speculation easier. When money is cheap, investors often reach further for returns. Projects that would look questionable in a stricter environment suddenly receive funding, applause, and maybe a conference keynote with dramatic lighting.
Stage 3: The Social Proof Explosion
Once friends, influencers, coworkers, and relatives start talking about the same opportunity, emotional pressure rises. Nobody wants to be the responsible adult in a room full of people claiming they doubled their money before breakfast. This is where many investors abandon process and start chasing.
Stage 4: The Break
Bubbles usually break when expectations meet friction. Earnings disappoint. Rates rise. credit tightens. Fraud appears. Growth slows. A famous company fails. The story does not need to become false; it only needs to become less perfect. When prices assume perfection, even “pretty good” can be a disaster.
How Investors Can Survive Animal Spirits
The goal is not to become emotionless. That would make you either a robot or the least fun person at Thanksgiving. The goal is to build rules that protect you when emotions run hot.
First, know what you own. If you cannot explain how an investment makes money, why it should grow, and what could go wrong, you are not investing; you are financially cosplaying. Second, position size matters. A speculative investment that is 2% of your portfolio is entertainment with upside. The same investment at 80% is a stress test for your blood pressure.
Third, diversify. Concentrated bets feel brilliant when they work and catastrophic when they do not. Diversification will never make you the most exciting person in a bull market, but it may keep you solvent long enough to enjoy the next one.
Use a Bubble Checklist
Before buying into a hot market, ask a few boring but beautiful questions: What would make me sell? Am I relying on fundamentals or vibes? Has the price risen faster than earnings or adoption? Are people using debt to buy? Are skeptics being laughed out of the room? Would I still want this asset if the price fell 50%?
If those questions make you uncomfortable, good. Discomfort is often cheaper than tuition at the University of Market Pain.
Experiences Related to “Animal Spirits: This is a Bubble”
Most investors do not experience bubbles as textbook diagrams. They experience them as conversations. A cousin mentions a stock that “can’t lose.” A coworker starts checking prices every five minutes. A friend who previously thought an ETF was a type of sandwich suddenly has strong opinions about options trading. At first, it is funny. Then it is persuasive. Then it becomes strangely hard to stay disciplined.
One of the most common bubble experiences is regret before the crash even happens. Imagine watching a hot asset rise 20%, then 50%, then 200% while you sit in a diversified portfolio that behaves like a responsible adult with a bedtime. You begin to feel silly. Your careful plan feels slow. The market seems to be rewarding everyone except the person who read the risk section.
That emotional pain is real. Missing out can feel like losing money, even when you have not lost a dollar. This is where animal spirits become powerful. They do not need to convince you with facts; they only need to make patience feel embarrassing.
Another familiar experience is the “small starter position” that quietly becomes a personality. An investor buys a little of something speculative just to participate. Then it rises. The gain feels validating. More money goes in. The investor starts reading only bullish commentary. Criticism feels personal. Soon the investment is no longer a position; it is a belief system with a ticker symbol.
Then comes the first serious drop. At first, believers call it healthy consolidation. Then a buying opportunity. Then manipulation. Then panic. The same crowd that said price did not matter suddenly checks price constantly. The emotional cycle flips from greed to fear so fast it should come with a seatbelt.
The healthiest investors learn from these experiences without pretending they are above them. Everyone is vulnerable to a good story. Everyone likes making money. Everyone feels a little jealous when someone else gets rich quickly. The difference is not intelligence; it is preparation. Smart investors build systems before the bubble arrives. They rebalance. They limit position sizes. They write down why they bought. They avoid borrowing against dreams. They leave room for being wrong.
The biggest lesson from “Animal Spirits: This is a Bubble” is not that optimism is bad. Optimism builds companies, funds innovation, and gives markets their forward motion. The lesson is that optimism needs a chaperone. Without discipline, confidence can become speculation, speculation can become mania, and mania can become a very expensive story people tell later using the phrase, “I should have known.”
In the end, bubbles are not just about markets. They are about human nature. We want progress. We want shortcuts. We want to believe we are early, clever, and destined for the winner’s circle. Sometimes we are. Sometimes we are just standing in a very crowded room while the music gets louder.
Conclusion: Respect the Bubble, But Don’t Worship It
“Animal Spirits: This is a Bubble” is more than a catchy market phrase. It is a reminder that investing is part math, part psychology, and part crowd control. Bubbles happen because humans are hopeful creatures. We chase stories, copy winners, ignore warnings, and convince ourselves that risk has politely retired.
The best defense is not cynicism. It is discipline. Real innovation deserves attention. Rising markets can create wealth. But no trend is so powerful that price stops mattering. When animal spirits roar, investors should listen carefully, think independently, and keep one hand near the risk-management button.
A bubble can be thrilling on the way up and humbling on the way down. Enjoy the excitement if you must, but do not confuse excitement with evidence. The market has a long memory and a wicked sense of humor.