Buying a house at the top of the market feels a little like jumping onto a moving treadmill while holding a tray of coffee. You know millions of people have done it successfully. You also know one poorly timed step could make you question every life decision since middle school. When home prices are high, mortgage rates are stubborn, and every listing seems to come with either a bidding war or a mysterious “seller credit,” the decision becomes more than math. It becomes psychology.
That is where “animal spirits” enter the picture. In economics, animal spirits describe the emotions, confidence, fear, and gut feelings that influence financial decisions. Housing is full of them. Buyers do not simply compare interest rates and square footage like robots wearing sensible shoes. They imagine Thanksgiving dinners, future babies, dogs with muddy paws, backyard barbecues, and the quiet satisfaction of never again asking a landlord if painting one wall is “allowed.”
But when the market feels expensive, those dreams collide with a very practical question: Is buying a house at the top of the market a terrible ideaor just a scary but reasonable long-term move?
What Does “Buying at the Top of the Market” Really Mean?
The phrase “top of the market” sounds dramatic, as if someone rings a bell and announces, “Congratulations, everyone, prices are now officially ridiculous.” Sadly, the housing market does not offer that kind of customer service. A market top is usually only obvious in hindsight.
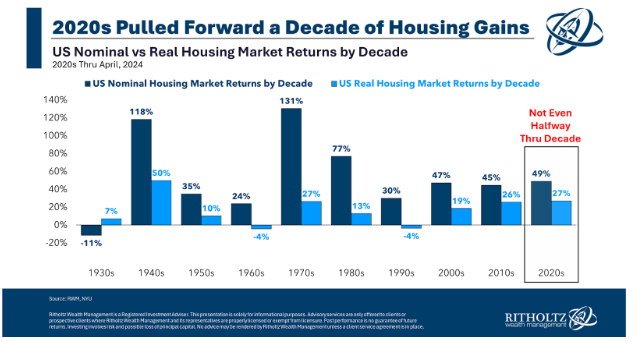
In real estate, buying at the top can mean several things. It may mean purchasing when home prices are near record highs. It may mean buying when mortgage rates make monthly payments painfully large. It may mean entering a local market where inventory is tight, sellers still have leverage, and buyers are stretching budgets just to compete. Sometimes it means all three, which is when your mortgage calculator starts looking at you like, “Are we really doing this?”
The important point is that the housing market is not one national monolith. A cooling Sun Belt suburb, a still-hot Northeast town, a luxury condo market, and a starter-home neighborhood can all behave differently at the same time. National headlines are useful, but your actual decision happens at the ZIP-code level.
The Current Housing Mood: Expensive, Uneven, and Emotional
Recent U.S. housing data shows a market that is not exactly booming, but not exactly cheap either. Existing-home sales have remained sluggish, largely because affordability is still a major challenge. Mortgage rates have stayed elevated compared with the ultra-low-rate years, and many owners who locked in cheap mortgages are reluctant to sell. That “lock-in effect” keeps inventory tighter than buyers would like, especially for affordable starter homes.
At the same time, inventory has improved in some areas, new-home supply is more available than existing-home supply, and builders in certain markets have used incentives such as mortgage-rate buydowns or price adjustments to attract buyers. In plain English: buyers are not powerless everywhere, but they are not shopping in a clearance aisle either.
This is the strange emotional soup of today’s housing market. Sellers still remember peak pandemic-era bidding wars. Buyers remember rates below 3 percent and feel personally offended by anything starting with a six. Builders are trying to move inventory without panicking. Agents are telling everyone to “date the rate,” which sounds like advice from a real estate rom-com. Meanwhile, buyers are asking the only question that matters: “Can I afford this without turning into a financially haunted person?”
Why Animal Spirits Matter So Much in Real Estate
Housing is the most emotional asset most people will ever buy. Stocks are numbers on a screen. A house has a smell, a street, a school district, a porch, and possibly one extremely questionable bathroom tile choice from 1997. That emotional weight can push buyers toward smart long-term decisionsor into dangerous overconfidence.
Fear of Missing Out
FOMO is one of the strongest animal spirits in real estate. When buyers watch prices rise for years, they begin to feel that waiting is the same as losing. A house listed at $450,000 today might be $475,000 next year, they think. If rates drop, competition could explode. If they wait for the perfect moment, they may end up waiting forever.
That fear is not always irrational. Housing supply constraints are real in many U.S. markets, and desirable neighborhoods can remain competitive even when national demand cools. But FOMO becomes dangerous when it makes buyers ignore inspection issues, waive protections, or accept a monthly payment that leaves no room for life’s favorite surprise guests: car repairs, medical bills, and broken water heaters.
Fear of Regret
The opposite emotion is just as powerful. Some buyers worry that the moment they close, prices will fall and their new home will become a very expensive lesson in timing. This fear can be especially strong when headlines mention slowing appreciation, price cuts, or homes sitting longer on the market.
But regret cuts both ways. A buyer who waits for a crash that never comes may regret missing a home that fit their needs, budget, and lifestyle. In housing, the goal is not to predict the perfect bottom. The goal is to avoid a decision that depends on perfection.
Overconfidence
Overconfidence sounds like this: “We can stretch now because income will definitely rise.” Maybe it will. Maybe it will not. Job markets change. Bonuses disappear. Property taxes rise. Insurance premiums do not ask for permission before becoming annoying. Buying at the top of the market requires humility. The house should still work if life is merely normal, not only if everything goes according to the highlight reel.
The Real Question: Price or Payment?
Many buyers focus on the purchase price because it is the big shiny number. But the monthly payment is the number that moves into your checking account and starts eating snacks. Mortgage rate, property taxes, insurance, homeowners association fees, maintenance, and utilities all determine the true cost of ownership.
A $450,000 house at a low interest rate may feel easier than a $410,000 house at a much higher rate. This is why affordability can remain strained even when price growth slows. Buyers should run payment scenarios, not just price scenarios. Ask what happens if insurance rises. Ask what happens if taxes reset after purchase. Ask what happens if a roof repair appears before your emergency fund has recovered from the down payment.
A helpful rule is to separate “approved” from “comfortable.” A lender may approve you for a payment that technically fits underwriting standards. That does not mean the payment fits your actual life. Banks do not know how often your cousin gets married in destination locations. They do not know that your dog eats prescription food. They do not know your deep emotional commitment to takeout on Fridays. Your budget knows.
When Buying Near the Top Can Still Make Sense
Buying at a high point is not automatically a mistake. Plenty of homeowners have purchased during expensive periods and done fine over time. Real estate rewards long holding periods, stable financing, and practical decision-making more than heroic market timing.
You Plan to Stay Long Enough
If you expect to own the home for seven to ten years or longer, short-term price swings become less important. A home bought near a local peak may dip in value for a period, but time can help absorb that volatility. The danger is buying at the top and needing to sell quickly. Transaction costs are high, and a short holding period leaves little room for recovery.
The Payment Fits Without Fantasy Math
A home can be expensive and still be reasonable if the payment is sustainable. The safest buyers are not necessarily those who get the lowest price. They are the ones who keep enough cash after closing, avoid draining every account, and still have room to save, maintain the property, and live a human life.
The Home Solves a Real Need
Buying makes more sense when the house solves a durable life problem: a stable school district, room for a growing family, proximity to work, multigenerational living, or escaping rent increases in a market where ownership is manageable. It makes less sense when the main motivation is “everyone else is doing it” or “my landlord raised rent and I am emotionally ready for revenge.”
When Buying at the Top Is Risky
The biggest red flag is stretching so far that the house becomes the only thing you can afford. Homeownership is not just a mortgage. It is maintenance, repairs, taxes, insurance, furniture, tools, lawn care, and at least one mysterious trip to the hardware store where you spend $87 and still do not own the thing you actually needed.
Buying is also risky if your job situation is unstable, your emergency fund is thin, or your local market depends heavily on one employer or one volatile industry. A home should add stability, not turn every paycheck into a cliffhanger.
Another risk is assuming refinancing will save you. Rates may fall, but they do not have to fall on your schedule. Even if they do, refinancing comes with costs and requires qualification. “I can refinance later” should be a bonus possibility, not the foundation of the purchase.
How to Buy Smarter in an Expensive Market
In a high-priced housing market, discipline matters more than drama. The smartest buyers act less like gamblers and more like patient business owners evaluating an asset they also plan to sleep inside.
1. Shop Below Your Maximum
Your maximum budget is not a target. It is a fence. Shop below it when possible so you have room for negotiation, repairs, and unexpected costs. A slightly smaller house with a calmer payment can be a better life decision than a dream home that makes every grocery receipt feel threatening.
2. Compare New and Existing Homes
In some markets, new construction may offer incentives that existing-home sellers do not. Builders may provide closing-cost assistance, rate buydowns, or design credits. Existing homes may have better locations, mature neighborhoods, or more negotiating room if they have been sitting. Compare the full package, not just the list price.
3. Study Days on Market and Price Cuts
Local trends matter. If homes are selling in three days above asking, you are in a different negotiation environment than a market where listings sit for 45 days and sellers quietly reduce prices. Ask your agent for recent comparable sales, not just active listings. Sellers can ask anything. Closed sales tell you what buyers actually paid.
4. Keep Inspection Protection
In hot markets, buyers sometimes waive inspections to compete. That can be costly. A home inspection does not guarantee perfection, but it gives you information. At minimum, understand what you are buying. Surprise foundation issues have a unique way of making granite countertops feel less exciting.
5. Build a Post-Closing Cash Cushion
Do not spend every dollar on the down payment. The first year of homeownership often comes with expenses that renters never had to think about: filters, tools, pest control, appliance repairs, landscaping, and the sudden realization that curtains are somehow expensive. Cash reserves are not boring. They are emotional support in bank-account form.
Specific Example: The “Top of Market” Buyer
Imagine a couple buying a $500,000 home with a 10 percent down payment. They are approved, excited, and slightly terrified. The neighborhood is strong, the schools are good, and they plan to stay for at least ten years. But the monthly payment is near the edge of comfort.
A risky version of this buyer empties savings, skips inspection, assumes a refinance within two years, and buys furniture on credit because “the house needs to look finished.” That is not homeownership. That is a financial obstacle course.
A stronger version negotiates seller credits, keeps six months of essential expenses, chooses a payment that still allows retirement contributions, and accepts that the guest room can remain suspiciously empty for a while. Same market. Same house price. Very different risk profile.
Should You Wait for Prices to Fall?
Waiting can be smart if your budget is not ready, your job is uncertain, or the available homes do not meet your needs. Patience is underrated, especially in a market where affordability is stretched. Renting for another year is not failure. Sometimes it is strategy with a lease.
However, waiting solely for a major crash can be frustrating. Housing downturns are uneven. Prices may fall in some metros while staying firm in others. If mortgage rates decline, more buyers may return, which can support prices. If rates rise, prices may soften, but payments may not improve. That is the housing market’s favorite trick: giving with one hand and stealing your snacks with the other.
The better question is not “Will the market fall?” It is “What price and payment would make sense for me even if the market moves sideways or dips temporarily?”
The Personal Side of Buying at the Top
There is a difference between a house as an investment and a house as a life platform. A primary residence is not just a spreadsheet. It is where routines happen. It is where kids grow, careers change, dinners burn, friends visit, and someone eventually argues about thermostat settings.
That does not mean emotions should run the show. It means the best housing decisions combine head and heart. The heart chooses a home that fits your life. The head makes sure the home does not quietly mug your future.
Experience-Based Reflections: What Buyers Learn After the Closing Table
People who buy near the top of the market often describe the experience in two stages: before closing and after moving in. Before closing, everything feels like a financial thunderstorm. Buyers refresh mortgage rates, compare comps, second-guess the offer, and wonder whether they should have waited for “the correction” that every online comment section promises is arriving any minute now. After moving in, the conversation changes. The house becomes less of a market chart and more of a daily reality.
One common lesson is that the monthly payment matters more than the opinion of strangers. A buyer can survive hearing that they “overpaid” if the payment is comfortable and the home fits their life. They will have a much harder time if they bought mainly to win a bidding war and now feel trapped by the cost. Victory feels different when the trophy comes with a 30-year payment schedule.
Another lesson is that maintenance arrives quickly. New homeowners often budget for the mortgage but underestimate the small expenses that come marching in like tiny financial ducks: a ladder, a lawn mower, better locks, paint, filters, light fixtures, plumbing parts, and that one appliance that waits until the first holiday weekend to become dramatic. Buyers who keep cash after closing usually feel more confident. Buyers who spend everything upfront may feel house-rich and peace-of-mind poor.
Many buyers also learn that local market quality matters more than national noise. A home in a neighborhood with strong schools, short commute times, limited supply, and steady demand may hold up better than a prettier house in a weaker location. Real estate has an old sayinglocation, location, locationbut in expensive markets, it should probably be expanded to location, payment, cash reserves, and please read the inspection report.
The emotional experience is real too. Some buyers feel nervous for months after closing, especially if headlines turn negative. That anxiety often fades when the home starts doing its job. The first birthday party, the first quiet morning coffee, the first time a renter friend says, “Wait, you can just change the light fixture?”these moments remind buyers that a primary home is not priced only by market value. It also has use value.
Still, the happiest buyers tend to be the ones who avoided fantasy assumptions. They did not rely on immediate appreciation. They did not need rates to drop. They did not assume every room had to be renovated in year one. They treated the first few years as a stabilization period. They learned the house, built savings back up, handled repairs in order of importance, and resisted the urge to turn every design idea into a same-week purchase.
Another practical experience is that negotiation does not end at price. In a cooler pocket of the market, buyers may get more value from seller credits, repair concessions, temporary rate buydowns, or closing-cost help than from a small price reduction. A lower price is nice, but cash at closing and a lower initial payment can matter more to real-life affordability. Smart buyers ask, “What structure improves my risk?” not simply, “How do I win?”
Finally, buyers who succeed at the top of the market usually make peace with uncertainty. They accept that nobody knows the exact peak. They focus on controllable factors: budget, loan terms, inspection, location, time horizon, emergency savings, and lifestyle fit. That mindset does not make the purchase risk-free, but it makes the risk understandable. And in real estate, understandable risk is far better than emotional chaos wearing a welcome mat.
Conclusion: Buy the Home, Not the Hype
Buying a house at the top of the market is not automatically foolish. It is also not automatically brave. It is a decision that depends on affordability, time horizon, local market conditions, personal stability, and emotional discipline. Animal spirits will always be part of real estate because homes are deeply personal. The trick is to let emotion tell you what matters, while letting math decide what is sustainable.
If the home fits your life, the payment fits your budget, and you plan to stay long enough to ride out market cycles, buying near a high point can still be a sound decision. If the purchase depends on perfect appreciation, quick refinancing, or heroic budgeting, the market may not be the real problem. The plan is.
The best home purchase is not the one that impresses your friends, defeats another buyer, or perfectly times the market. It is the one you can afford, maintain, enjoy, and keep. In a market full of animal spirits, that kind of calm confidence may be the rarest asset of all.
Note: This article is written for general educational and editorial publishing purposes. It is not personal financial, legal, tax, or mortgage advice. Readers should evaluate their own budget, local market, loan terms, and long-term plans before making a home purchase.