If your house needs a new roof, better insulation, hurricane shutters, solar panels, or an HVAC system that doesn’t sound like it’s auditioning for a monster movie, you may have run into something called a PACE loan. PACE stands for Property Assessed Clean Energy, and it’s one of the more unusual ways to pay for home upgrades in the United States.
Unusual does not automatically mean bad. It also does not automatically mean smart. That is the whole point of this article.
PACE financing can help homeowners get major upgrades without a big upfront payment. It can spread costs over many years, and in the right situation, it can make a project possible sooner rather than later. But it also comes with real drawbacks, especially around property tax bills, mortgage rules, refinancing, and selling your home. In other words, PACE can be a useful tool, but it is definitely not “free money wearing a green cape.”
Below is a plain-English look at the pros and cons of PACE loans, how they work, who they may fit, and when another financing option might be the safer move.
What Is a PACE Loan?
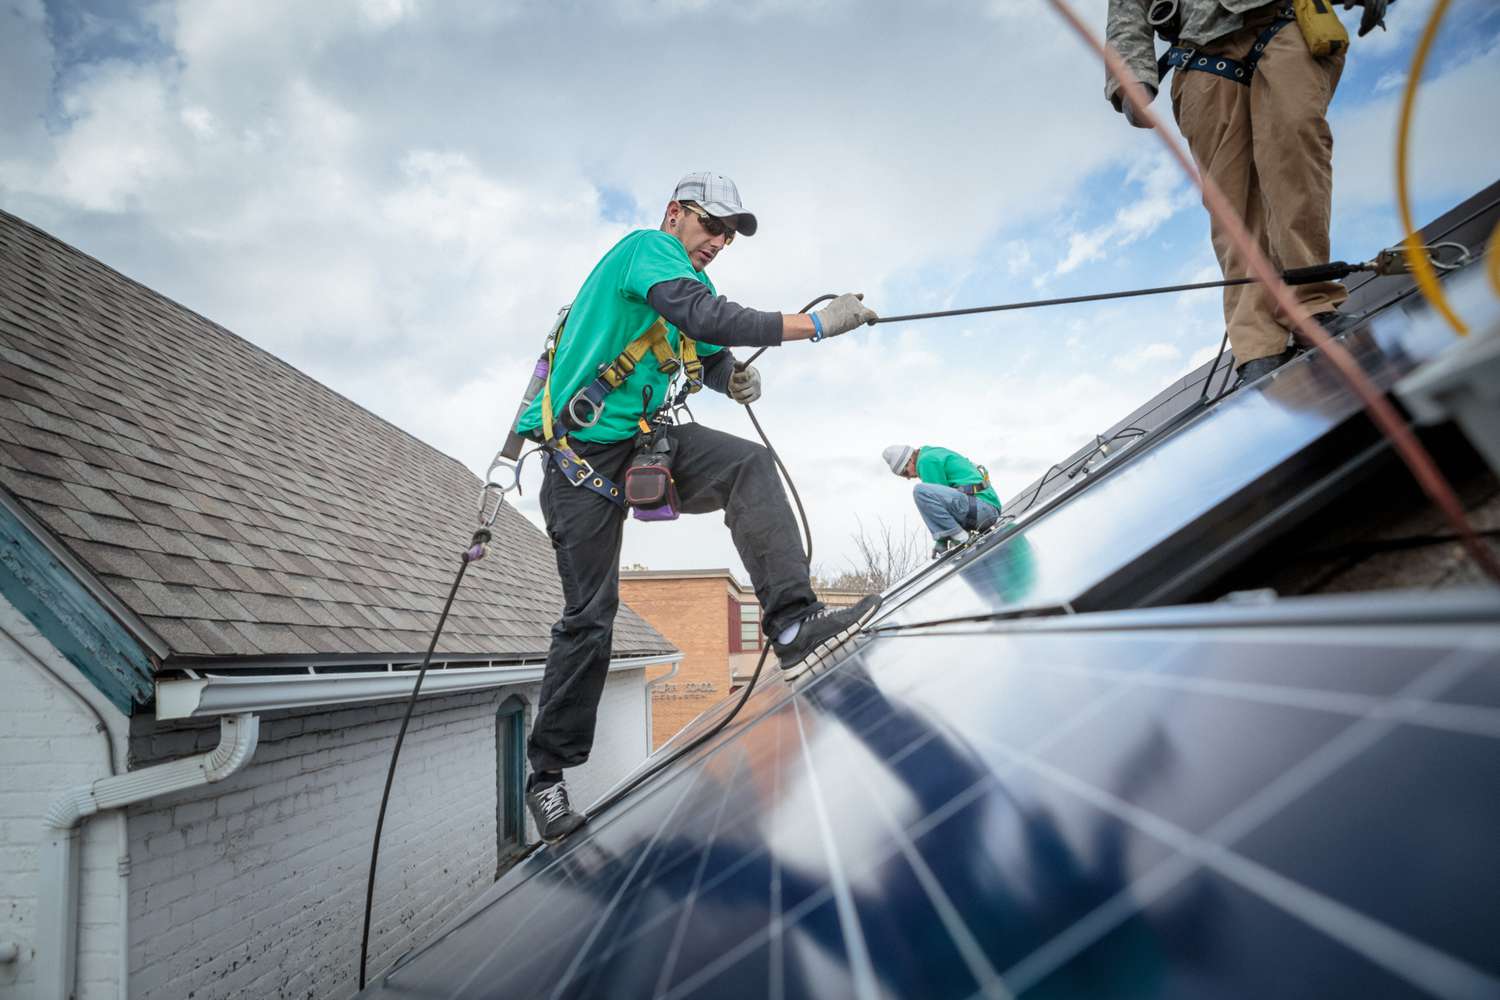
A PACE loan is financing used for eligible home improvements, usually upgrades tied to energy efficiency, water efficiency, renewable energy, or home resiliency. Depending on the program and location, that may include things like solar panels, impact windows, roofing, insulation, efficient HVAC systems, water-saving improvements, or storm-hardening work.
Here is the twist: the money is typically repaid through a special assessment added to your property tax bill, rather than through a standard monthly installment loan paid directly to a bank. That structure is what makes PACE different from a personal loan, HELOC, or traditional home improvement loan.
PACE financing is usually offered through programs authorized by state and local governments, but private companies often handle the origination and administration. So while it can sound very government-y, the actual financing is still real debt tied to your home. That part matters. A lot.
How PACE Financing Works
In a typical setup, a homeowner applies for financing for an approved upgrade. If the project qualifies and the homeowner is eligible, the funds are used to pay for the improvement. Repayment then shows up as part of the property tax obligation over a long term, often 10 to 30 years.
That arrangement can feel convenient because it avoids a large upfront payment and may offer a longer payoff period than some other financing options. But convenience can be sneaky. When the bill is bundled into property taxes, some homeowners underestimate how much their total housing cost is about to rise.
Also important: a PACE obligation can interact with your mortgage in ways that regular consumer loans often do not. Some mortgage investors and lenders are cautious about PACE liens, especially when lien priority is involved. That is one reason PACE has remained a niche product instead of becoming the default answer for every green home upgrade.
The Pros of PACE Loans
1. You may be able to start a big upgrade with little or no upfront cash
The most obvious benefit is access. Many homeowners want energy-efficient upgrades but do not have tens of thousands of dollars sitting around waiting to become a new roof or solar array. PACE can fund a large portion, and sometimes all, of an eligible project cost. That can make urgent repairs or efficiency improvements possible right away.
For example, imagine a homeowner in a hot climate whose aging air conditioner is failing. Replacing it with a more efficient system may cut utility waste and improve comfort fast. If cash is tight, PACE can remove the biggest barrier: the giant up-front bill that makes people suddenly very interested in box fans.
2. Longer repayment terms can lower the immediate payment pressure
Traditional financing might come with a shorter term and a higher monthly payment. PACE terms are often longer, which may make the periodic cost easier to absorb. That can be attractive for homeowners who need the work done now but want to spread repayment across many years.
That does not mean it is cheaper overall. It usually means it feels more manageable in the short run. There is a difference, and it is a very expensive difference if you ignore it.
3. Eligible improvements can reduce utility costs or improve resiliency
PACE is commonly used for upgrades that may lower energy or water use or improve resistance to storms and disasters. Better insulation, efficient HVAC equipment, solar, impact-resistant windows, and similar improvements can create real long-term value for the household.
When the project is well chosen, homeowners may benefit from lower bills, more comfort, better durability, and less deferred maintenance. The upgrade itself may be smart even if the financing choice is not. That is why it is critical to evaluate the project and the financing separately.
4. It may help homeowners who do not want to use credit cards or unsecured loans
For some borrowers, the alternatives are ugly. Credit cards can be brutally expensive. Personal loans may have shorter terms or smaller limits. PACE can look appealing because it is tied to the property and designed for a specific improvement category.
In the right case, that can be better than putting a major home upgrade on revolving debt and pretending future-you will “figure it out.” Future-you would like a word.
5. In some situations, the obligation may remain with the property
One of the most talked-about features of PACE is that the obligation is tied to the property assessment structure, not just to a standard note like many loans. In some circumstances, that means the repayment obligation may continue with the property when it is sold.
This can sound like a huge advantage. And sometimes it is. If the next owner is willing and able to take on a property with the assessment in place, the seller may avoid paying off the full balance at closing. But this is not automatic magic. In real transactions, buyers and their lenders may still require payoff before closing. So this “benefit” is more conditional than many marketing blurbs make it seem.
The Cons of PACE Loans
1. Your property tax bill goes up, and that can cause payment shock
This is the big one. Because repayment is added to your property tax bill, your housing expense can jump in a way that feels less obvious than a standard loan payment. If you escrow taxes through your mortgage servicer, the servicer may adjust your escrow amount upward, which can increase your monthly mortgage payment.
That is where some homeowners get blindsided. They focus on the upgrade, the contractor, and the dream of lower utility bills. Then the tax bill or escrow adjustment arrives like an unwanted plot twist. If your budget is already tight, PACE can become stressful very quickly.
2. Falling behind can put your home at risk
PACE is secured by your home. If you fail to pay the property tax bill that includes the PACE assessment, you can end up in delinquency and potentially face foreclosure risk. This is not a casual “oops, I missed a subscription renewal” problem. Housing-related debt deserves grown-up attention, even when the sales pitch is wearing green language and smiling contractor photos.
That risk is one reason consumer advocates and regulators have spent years pushing for stronger disclosures and underwriting standards in residential PACE transactions.
3. Mortgage and lien issues can make things complicated fast
PACE has long raised concerns in the mortgage world because of how the lien can interact with the first mortgage. Fannie Mae has restrictions on purchasing mortgage loans secured by properties with outstanding PACE obligations that take priority over the first mortgage lien. That means the existence and structure of a PACE obligation can affect mortgage eligibility, refinancing, and lender appetite.
Translation: your house may be getting nicer, but your financing file may be getting messier.
4. Selling or refinancing may not be as simple as you hoped
Many homeowners hear that PACE “stays with the property” and assume that means resale will be easy. Sometimes it is. Sometimes it absolutely is not. A buyer may be unwilling to inherit the assessment. A buyer’s mortgage lender may require the PACE obligation to be paid off. A future refinance may also be harder, depending on the lender, the loan program, and market conditions.
So yes, transfer is possible in some settings. But in the real world, payoff at sale or refinance is still a very real possibility. If you expect to move soon, PACE can become a lot less charming.
5. Total borrowing costs may be higher than other options
Low upfront cost does not equal low total cost. Between interest, fees, and long repayment periods, the full cost of a PACE-financed project can be meaningful. Borrowers should compare the annual percentage rate, total finance charge, payment schedule, prepayment rules, and any contractor-related pricing differences.
Sometimes the right question is not “Can I afford this upgrade today?” It is “Which financing method gives me the best long-term deal without wrecking flexibility later?” That question is less exciting, but it saves more money.
6. PACE is not available everywhere
Residential PACE remains limited geographically. In practice, availability depends on state law, local program participation, and the property’s location. So even if PACE sounds perfect on paper, it may not exist where you live.
That limited availability also means many real estate agents, loan officers, and even some homeowners are not deeply familiar with it. Lack of familiarity can create confusion when a home is sold or refinanced.
Who Might Benefit Most from a PACE Loan?
PACE financing may fit homeowners who:
– need an eligible upgrade now rather than later;
– have enough budget room to absorb a higher property tax-related payment;
– plan to stay in the home long enough for the upgrade benefits to matter;
– understand the lien, tax, escrow, and resale implications; and
– have already compared PACE against at least two or three other financing options.
PACE may be less suitable for homeowners who:
– expect to sell soon;
– are already stretched on monthly housing costs;
– may refinance in the near future;
– have an existing mortgage with strict restrictions or limited flexibility; or
– have not fully reviewed the long-term cost of the financing.
Alternatives to Compare Before You Sign Anything
HELOC or home equity loan
A HELOC lets you borrow against home equity on a revolving basis, while a home equity loan provides a lump sum. These can be good comparison points if you have strong equity and want more conventional loan mechanics. They still put your home on the line, but they may offer clearer structures for some borrowers.
Cash-out refinance
A cash-out refinance replaces your existing mortgage with a larger one and gives you the difference in cash. This can work for major repairs or upgrades, especially if the new mortgage terms are favorable. But it changes your primary mortgage, which can be a bigger move than many homeowners really want.
FHA 203(k) rehabilitation loan
If you are buying or refinancing a home that needs work, the FHA 203(k) program can package the purchase or refinance and renovation costs into a single mortgage. It is especially relevant when the project is broader than a narrow energy upgrade and includes repairs, modernization, or resilience improvements.
Specialized solar or contractor financing
For solar and certain efficiency upgrades, specialized loan products may offer competitive terms. The catch is that some come with dealer fees, promotional structures, or future payment jumps. So compare carefully and do not let a sales presentation bully your calculator.
Questions to Ask Before Choosing PACE
Before you sign, ask:
– What is the full APR and total repayment amount?
– How will this affect my property tax bill and mortgage escrow?
– What happens if I sell in two years?
– Will my buyer or their lender likely require payoff?
– Are there prepayment penalties or payoff fees?
– How does this compare with a HELOC, home equity loan, or cash-out refinance?
– Are the projected utility savings realistic, or are they just sales confetti?
If the person selling the project gets irritated when you ask detailed questions, that is not a sign to stop asking. That is a sign to ask slower.
Final Verdict: Is PACE Financing a Good Idea?
The pros and cons of PACE loans come down to one simple truth: PACE can be helpful for the right homeowner and the wrong move for the wrong homeowner.
On the plus side, it can open the door to valuable upgrades, reduce upfront cost barriers, and support improvements that make a home more efficient, comfortable, or resilient. On the negative side, it can raise your tax-related housing costs, create mortgage and resale complications, and expose you to serious risk if the payment becomes unaffordable.
The smartest way to view PACE is not as a miracle product and not as a scam by default. It is a specialized financing tool. Specialized tools are great when you know exactly what you are doing. They are less great when you grab them because a salesperson made them sound shiny.
If you are considering PACE, compare it carefully with other financing options, read every disclosure, and think ahead to resale, refinance, and your monthly budget. A home upgrade should improve your life, not quietly booby-trap your future closing table.
Homeowner Experiences and Real-World Lessons About PACE Financing
In real-world situations, homeowner experiences with PACE financing tend to fall into two camps: people who used it strategically and feel satisfied, and people who focused on the upgrade but underestimated the financing details.
The satisfied group usually shares a few traits. They often had a very specific project, such as replacing an old roof, adding impact-resistant windows, or installing a more efficient HVAC system before a system failure turned into a sweaty family emergency. They compared options first, understood that repayment would show up through property taxes, and planned their cash flow around that reality. For these homeowners, PACE was not exciting because it was cheap. It was useful because it was available, predictable enough, and tied to a project they believed was worth doing.
Another common positive experience comes from homeowners who planned to stay put for a long time. They were less worried about resale and more focused on monthly comfort, utility savings, and durability. If a family expects to stay in the home for many years, a long-term repayment structure can feel reasonable, especially when the improvement solves an immediate quality-of-life problem. A quieter HVAC system, a better-insulated attic, or storm-resistant upgrades may not make dinner parties more thrilling, but they can absolutely make a home more livable.
The less positive stories usually involve surprise. Not always fraud. Not always disaster. Just surprise, which is expensive enough on its own.
Some homeowners report that they did not fully understand how the assessment would affect their total housing payment. They heard “no big upfront cost” and mentally filed that under “good news,” but they did not model what would happen when the tax bill rose or when the mortgage servicer adjusted escrow. Others discovered the biggest headache later, when they tried to sell or refinance and learned that the PACE balance had become part of the negotiation. Suddenly the upgrade was not just a kitchen-table financial decision anymore. It was a closing-table issue with extra paperwork and fewer smiles.
There is also a softer lesson that comes up again and again: homeowners often confuse a good project with a good financing method. Replacing a failing roof may be the right decision. Installing efficient windows may be the right decision. Hardening a home against storms may be the right decision. But that still does not answer whether PACE is the best way to pay for it. Smart borrowers separate those two choices instead of blending them into one emotional yes.
The most practical takeaway from homeowner experience is simple: the more rushed the sales process feels, the more slowly you should move. Good financing holds up under scrutiny. If a deal only makes sense when you stop asking questions, it probably never made sense at all.