Note: This article is for educational purposes only and should not be read as personal financial advice. Investing involves risk, and nobody, not even a person with Charlie Munger’s eyebrows and brainpower, can remove uncertainty from markets.
Introduction: Why Charlie Munger Still Matters
Charlie Munger was not the loudest man in investing. He did not dance in front of earnings charts, shout stock tips, or pretend the market was a slot machine wearing a necktie. Instead, he became famous for something far rarer: clear thinking.
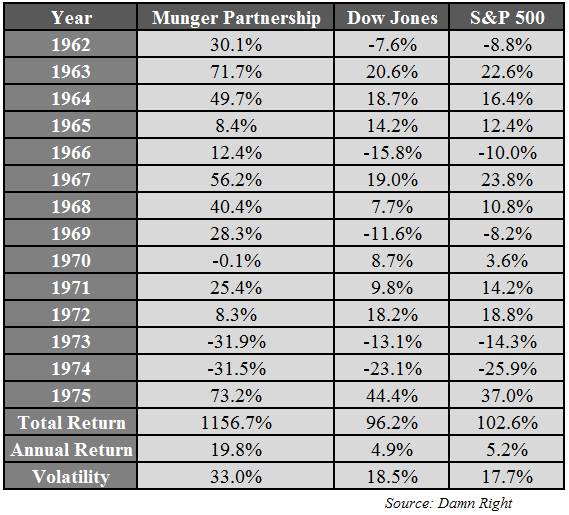
As Warren Buffett’s long-time business partner and vice chairman of Berkshire Hathaway, Munger helped shape one of the most admired investing cultures in modern business. Buffett often received the spotlight, but Munger supplied much of the architecture: buy excellent businesses, avoid foolish behavior, think independently, and let time do the heavy lifting.
Charlie Munger’s investing principles are not complicated in the way Wall Street likes to make things complicated. There are no 47-screen dashboards, no mysterious “proprietary signals,” and no need to pretend you understand every macroeconomic ripple on Earth. His philosophy is built on patience, rationality, discipline, humility, and a deep respect for human psychology.
That is why Munger’s ideas remain useful for beginners, long-term investors, business owners, and anyone trying not to turn their portfolio into a cautionary campfire story.
Who Was Charlie Munger?
Charles Thomas Munger was an investor, lawyer, businessman, philanthropist, and famously blunt thinker. Born in Omaha, Nebraska, in 1924, he later became Warren Buffett’s closest partner at Berkshire Hathaway. Munger died in 2023 at age 99, just weeks before his 100th birthday, leaving behind a legacy that stretched far beyond balance sheets.
His greatest contribution to investing was not a single stock pick. It was a way of thinking. Munger pushed Buffett away from buying merely cheap, mediocre companies and toward buying high-quality businesses at fair prices. That shift helped Berkshire Hathaway evolve from a struggling textile company into a giant holding company with durable businesses, major equity investments, and a shareholder culture built on trust.
Charlie Munger’s Core Investing Principles
1. Buy Wonderful Businesses at Fair Prices
One of Munger’s most important lessons was that a cheap stock is not automatically a good investment. A bad business bought at a bargain price can still be a bad business. It is like buying discounted sushi from a gas station: the price may be attractive, but the consequences could be memorable for all the wrong reasons.
Munger preferred companies with durable competitive advantages, strong brands, pricing power, reliable earnings, and capable management. This approach influenced Berkshire Hathaway’s interest in businesses such as See’s Candies, Coca-Cola, American Express, and other companies with strong customer loyalty and long-term economics.
The principle is simple: price matters, but quality matters too. A wonderful business can compound value for decades, while a poor business may consume capital, attention, and emotional energy.
2. Stay Inside Your Circle of Competence
Munger believed investors should know the boundaries of their knowledge. The “circle of competence” means investing only in businesses and industries you can understand well enough to evaluate rationally.
This does not mean your circle must be huge. In fact, pretending to understand everything is one of the fastest ways to become the proud owner of expensive confusion. Munger’s point was that investors should define what they understand, admit what they do not, and avoid crossing into unfamiliar territory simply because everyone else is excited.
For a regular investor, this might mean avoiding businesses with unclear revenue models, complicated financial engineering, or technology you cannot explain without using the phrase “sort of like magic.”
3. Use Mental Models from Many Disciplines
Munger was famous for his “latticework of mental models.” He believed better decisions come from understanding big ideas across fields such as economics, psychology, mathematics, engineering, biology, history, and physics.
Why does this matter for investing? Because businesses are not just numbers on a spreadsheet. They are systems involving incentives, competition, human behavior, scarcity, feedback loops, brand loyalty, regulation, and probability.
An investor who understands incentives may better judge management behavior. An investor who understands psychology may avoid panic selling. An investor who understands basic probability may stop treating lucky outcomes as proof of genius. Munger wanted investors to think broadly because markets punish narrow thinking with enthusiasm.
4. Invert, Always Invert
One of Munger’s favorite thinking tools was inversion. Instead of only asking, “How do I succeed?” ask, “How do I fail?” Then avoid those mistakes.
In investing, inversion might look like this:
- How can I permanently lose money?
- How can I fool myself into overpaying?
- How can I become emotionally attached to a bad investment?
- How can fees, taxes, debt, or panic destroy my returns?
This approach is powerful because avoiding stupidity is often easier than achieving brilliance. You do not need to predict every winning stock. You do need to avoid obvious disasters: too much leverage, businesses you do not understand, dishonest managers, hype-driven buying, and selling good assets during temporary fear.
5. Demand a Margin of Safety
Munger respected the classic value investing idea of a margin of safety. A margin of safety means leaving room for error between what you pay and what you believe an investment is worth.
Business forecasts are never perfect. Interest rates change. Competitors appear. Consumer habits shift. Executives make mistakes. Sometimes the economy decides to throw furniture around the room. A margin of safety protects investors from being destroyed by normal uncertainty.
For Munger, risk was not just price volatility. Real risk was permanent loss of capital. A stock bouncing around in price is not necessarily dangerous if the underlying business remains strong. But overpaying for a weak business can be dangerous even if the chart looks calm for a while.
6. Be Patient, Then Be Decisive
Munger believed great opportunities are rare. That means investors should spend most of their time reading, thinking, waiting, and saying no. This is emotionally difficult because humans enjoy action. Wall Street enjoys action even more because action often creates fees.
Munger’s style was different. He believed in waiting for exceptional opportunities and acting decisively when the odds were clearly favorable. Patience was not laziness. It was preparation.
The lesson is not to sit forever doing nothing. The lesson is to avoid constant tinkering. A portfolio does not become smarter simply because its owner clicks buttons every Tuesday.
7. Let Compounding Work
Compounding is the quiet engine behind long-term wealth. It happens when returns generate more returns over time. Munger understood that unnecessary trading, emotional decisions, taxes, and fees can interrupt compounding.
The magic of compounding is not very dramatic at first. It looks boring. Then, after enough time, it looks obvious. Then, after even more time, people call it genius. Munger knew the genius was often in not interrupting the process.
This is why he admired businesses that could reinvest capital at high rates for long periods. A company with durable economics, honest management, and room to grow can become far more valuable over time than a cheap but stagnant company.
8. Understand Incentives
Munger often emphasized the power of incentives. People respond to rewards, penalties, status, fear, greed, and social pressure. Investors who ignore incentives are basically analyzing a football game while pretending the scoreboard does not exist.
In business analysis, incentives matter everywhere. How is management paid? Does leadership think like owners? Are salespeople rewarded for long-term customer value or short-term volume? Are financial results being massaged to hit bonuses?
Munger believed incentives could explain a great deal of human behavior. A smart investor studies not only what people say, but also what they are rewarded to do.
9. Avoid Envy, Greed, and Overconfidence
Munger’s investing principles are deeply connected to psychology. He understood that many investors do not fail because they lack intelligence. They fail because they lack emotional control.
Envy makes investors chase what recently went up. Greed makes them ignore risk. Fear makes them sell at the worst moment. Overconfidence makes them confuse a rising market with personal brilliance. Munger had little patience for these habits, probably because markets have even less patience.
His solution was rationality. Build systems. Use checklists. Seek disconfirming evidence. Stay humble. Do not let the crowd rent space in your brain unless it pays a very high security deposit.
10. Reputation and Integrity Matter
Munger believed reputation could be lost quickly and should be guarded carefully. This principle applied to both life and investing.
He warned against dealing with people of questionable character, even if the numbers looked attractive. A dishonest manager can destroy shareholder value. A toxic culture can ruin a business. A tempting opportunity tied to poor ethics may become expensive in ways that never appear in the first spreadsheet.
For Munger, good investing was not separate from good judgment. Integrity was not decorative. It was practical.
How Munger Changed Warren Buffett’s Investing Style
Before Munger’s influence, Buffett was heavily shaped by Benjamin Graham’s bargain-hunting style. Graham taught investors to look for stocks trading below intrinsic value, often called “cigar-butt” investing: finding discarded companies with one last puff of value left.
Munger helped Buffett move beyond that. He argued that it was often better to buy a truly excellent business at a fair price than a mediocre business at a very cheap price. This was not a rejection of value investing. It was an evolution of it.
The acquisition of See’s Candies became a classic example. See’s was not purchased because it was the cheapest asset on Earth. It was attractive because it had brand loyalty, pricing power, strong economics, and relatively modest capital needs. In plain English, people liked the chocolate enough to keep buying it even when prices rose a little. That is a beautiful business trait, and also a dangerous thing to discover when you are hungry.
Charlie Munger’s Checklist for Better Investing
Munger admired checklists because they reduce preventable mistakes. A practical Munger-style investing checklist might include:
Risk
What can go wrong? Is there a margin of safety? Could debt, competition, regulation, or poor management permanently damage the business?
Understanding
Can you explain how the company makes money? Do you understand its industry, customers, advantages, and threats?
Management
Are leaders honest, capable, and shareholder-oriented? Are incentives aligned with long-term value creation?
Valuation
Are you paying a sensible price compared with the company’s long-term earning power? Are your assumptions conservative?
Psychology
Are you buying because of rational analysis or because you fear missing out? What evidence would prove you wrong?
Opportunity Cost
Is this the best use of your capital compared with other available choices?
Common Mistakes Munger Would Warn Investors to Avoid
Munger’s philosophy is especially useful because it highlights what not to do. Many investors spend too much time searching for brilliance and too little time avoiding foolishness.
One common mistake is buying something you do not understand because it is popular. Another is overpaying for a good company after its story becomes fashionable. A third is using debt to chase returns, which can turn temporary volatility into permanent damage.
Munger would also warn against excessive trading. Every trade may create friction through spreads, taxes, fees, and mental distraction. More activity does not equal more intelligence. Sometimes it simply means the investor has confused motion with progress.
Why Munger’s Principles Work for Regular Investors
You do not need to run Berkshire Hathaway to benefit from Charlie Munger’s investing principles. In fact, his ideas may be most useful for ordinary investors because they encourage simplicity and discipline.
Regular investors can apply Munger’s wisdom by focusing on long-term ownership, avoiding hype, keeping costs low, studying businesses carefully, and building emotional resilience. They can also admit when a broad, diversified approach is more appropriate than trying to pick individual stocks.
The larger lesson is that investing success is not only about finding information. Everyone has information now. The challenge is judgment. Munger’s edge came from filtering information through rational models, psychological awareness, and decades of patient learning.
Experience-Based Lessons from Charlie Munger’s Investing Principles
One of the most practical experiences related to Charlie Munger’s investing principles is learning how uncomfortable patience feels. Many beginners assume patience means calm confidence. In reality, patience often feels like watching other people brag about quick profits while you sit quietly with a sensible plan. It can feel boring, even foolish, until the market cycle changes and the “geniuses” discover gravity.
A Munger-style investor learns that boredom is not always a problem. Sometimes boredom is the sound of discipline working. If you own a strong business or a diversified long-term portfolio, you do not need daily excitement. You need time, reasonable expectations, and the ability to avoid self-sabotage.
Another experience is discovering how hard it is to stay within your circle of competence. The modern market constantly throws shiny objects at investors: artificial intelligence themes, hot IPOs, crypto booms, turnaround stories, meme stocks, and companies with investor presentations that look like science fiction movie trailers. Some may become successful, but Munger’s question would be simple: do you truly understand the economics?
That question can save money. When you cannot explain how a company earns cash, what protects its profits, and why it should be worth more in the future, you are not investing with insight. You are guessing with extra paperwork.
A third experience is seeing how emotions distort decisions. Many people believe they will be brave during a market decline. Then prices fall, headlines turn dramatic, and suddenly bravery goes looking for snacks in another room. Munger’s principles prepare investors before panic arrives. If you already know what you own and why you own it, you are less likely to sell simply because the market is having a bad week.
Inversion is especially useful in real life. Before buying an investment, ask: “How could this go badly?” Maybe the company depends on one product. Maybe debt is too high. Maybe management has a history of promotional behavior. Maybe the valuation assumes perfection. This exercise does not make you pessimistic. It makes you prepared.
Another Munger-inspired experience is realizing that opportunity cost is everywhere. When you put money into one investment, you give up the chance to put it somewhere else. When you spend time studying a weak idea, you lose time that could be spent studying a better one. Munger’s discipline was not just about saying yes to great opportunities. It was about saying no repeatedly without feeling guilty.
Finally, Munger’s principles teach that investing is personal character under pressure. A person who is impatient, envious, careless, or unwilling to learn will struggle even with good information. A person who is rational, humble, curious, and disciplined has a major advantage. The market does not reward people for sounding smart at dinner. It rewards those who make fewer serious mistakes and allow good decisions to compound.
That is the real experience of applying Charlie Munger’s investing principles: you slowly become less interested in noise and more interested in judgment. You stop asking, “What is everyone buying?” and start asking, “What makes sense?” In a world addicted to speed, that kind of thinking feels almost rebellious. Munger would probably approve, though he might add that approval is not the point. Being right over time is.
Conclusion: The Munger Way Is Simple, Not Easy
Charlie Munger’s investing principles can be summarized in a few powerful ideas: buy quality, stay rational, avoid stupidity, think long term, understand incentives, use mental models, demand a margin of safety, and never underestimate psychology.
These ideas sound simple. That is part of their genius. But simple does not mean easy. It is easy to talk about patience and hard to practice it when markets are falling. It is easy to praise rationality and hard to stay rational when everyone else is celebrating a bubble. It is easy to claim humility and hard to admit, “I do not understand this investment.”
Munger’s greatness came from doing the hard parts repeatedly for decades. He proved that investing is not just a numbers game. It is a thinking game, a behavior game, and sometimes a not-doing-something-stupid game.
For investors today, the best tribute to Charlie Munger is not memorizing his quotes. It is building a better mind: more patient, more curious, more skeptical, and less vulnerable to nonsense wearing a luxury watch.